Net worth is the simplest snapshot of your finances: everything you own minus everything you owe. The Federal Reserve defines it the same way, as the difference between a family’s gross assets and its liabilities.Source 1
Income shows what comes in each year; net worth shows what you’ve built up. This guide shows how to calculate yours with a worked example, what to count and what to leave out, and how it compares with the Federal Reserve’s latest figures by age.
The net worth formula
Net worth equals total assets minus total liabilities.
- total assets is everything you own that has value
- total liabilities is everything you owe
If you owe more than you own, your net worth is negative.
What counts as assets and liabilities
The Federal Reserve’s survey counts financial assets, such as bank accounts, CDs, bonds, stocks, investment funds and retirement accounts, and nonfinancial assets, such as vehicles, real estate and business equity.Source 1 For your own statement:
Assets:
- Checking, savings and money market accounts, and CDs
- Retirement accounts, such as 401(k)s and IRAs
- Investments, such as stocks, bonds and mutual funds in a brokerage account
- Your home and any other real estate, at what it would sell for
- Vehicles, at their current value
- A business you own
Liabilities:
- Mortgages and home equity loans
- Car loans
- Student loans
- Credit card balances
- Personal loans and any other money you owe
Furniture, clothes and other belongings rarely sell for much, so leave them out or count them cautiously. The Federal Reserve’s figures also leave out Social Security and employer-sponsored defined-benefit pensions.Source 1 If you have a pension, it’s simplest to leave it out too and treat it as future income.
How to calculate your net worth
- List what you own, using current balances from your statements and today’s market values for your home and car.
- List what you owe, using current balances rather than the original loan amounts.
- Subtract your total liabilities from your total assets.
- Repeat it once or twice a year, on about the same date, to see the trend.
A net worth example
Here’s a couple in their late 30s who own a home:
| Item | Amount |
|---|---|
| Checking and savings | $18,000 |
| 401(k) and IRA | $100,000 |
| Brokerage account | $9,000 |
| Home, at its estimated market value | $340,000 |
| Car, at what it would sell for today | $16,000 |
| Total assets | $483,000 |
| Mortgage | −$251,000 |
| Car loan | −$11,500 |
| Student loans | −$22,000 |
| Credit card balance | −$2,300 |
| Total liabilities | −$286,800 |
| Net worth | $196,200 |
They own $483,000 and owe $286,800, so their net worth is $196,200.
Two details are worth noticing. Their home equity, the home’s value minus the mortgage, is $89,000, or 45% of their net worth; without it, they’d have $107,200. And only $27,000 sits in accounts they could reach quickly without selling the home or dipping into retirement savings.
Median net worth by age
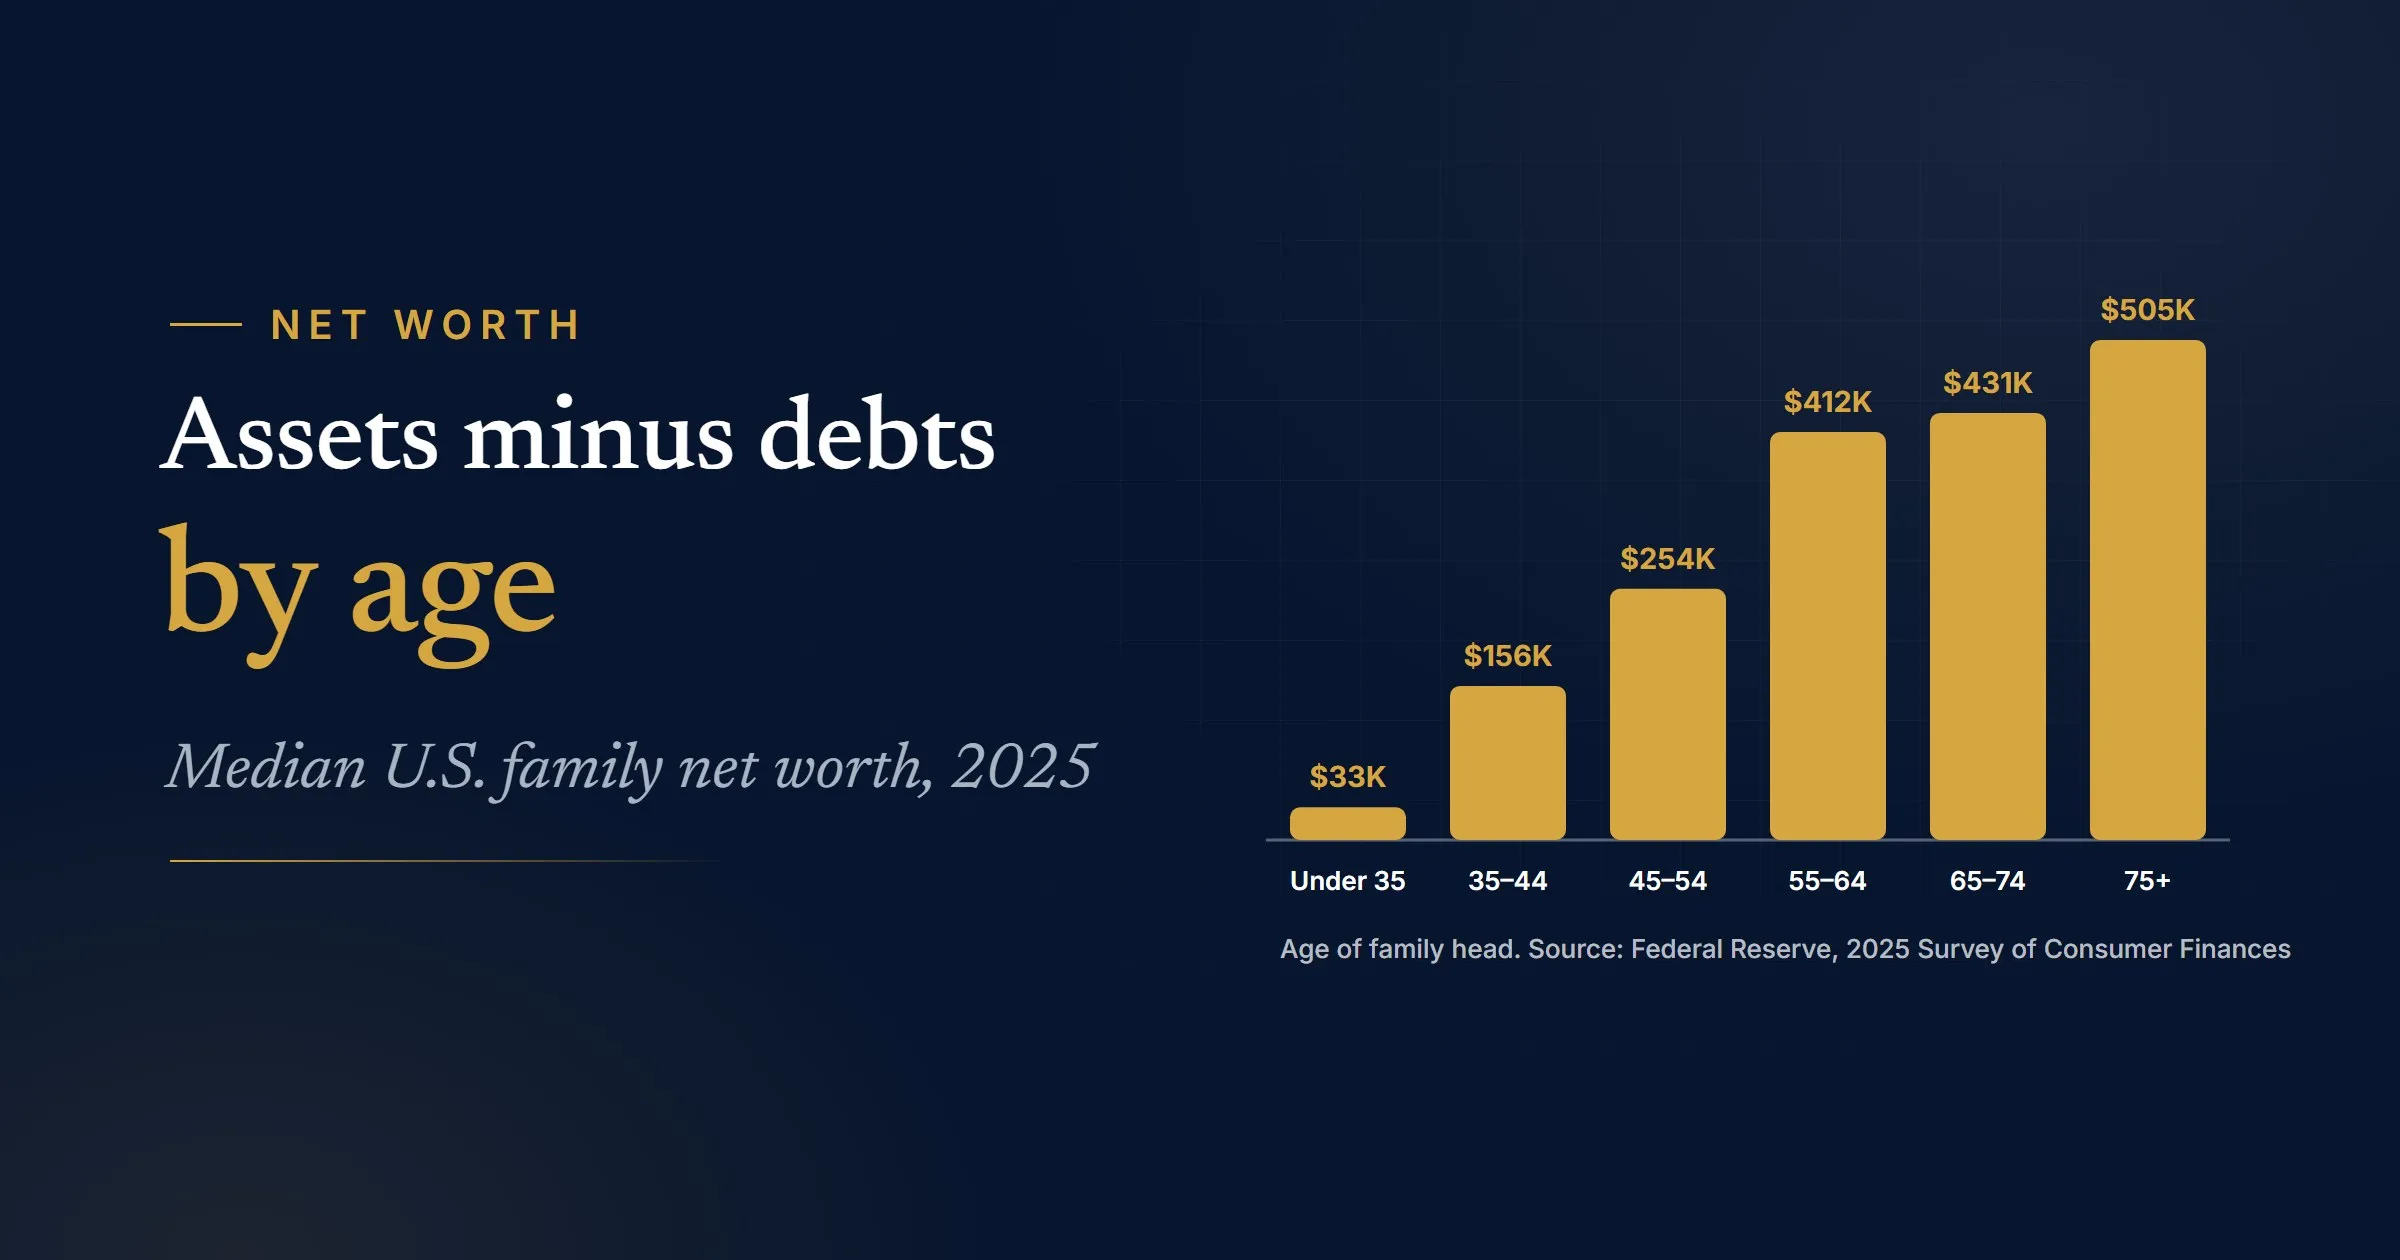
The Federal Reserve’s Survey of Consumer Finances, run every three years, gives the most detailed picture of what American families own and owe. Here’s what its 2025 survey, released in October 2026, found:Source 1
| Age of family head | Median | Mean |
|---|---|---|
| Under 35 | $33,000 | $135,400 |
| 35 to 44 | $155,600 | $681,900 |
| 45 to 54 | $253,700 | $1,244,500 |
| 55 to 64 | $411,900 | $1,878,000 |
| 65 to 74 | $431,300 | $1,897,600 |
| 75 and older | $504,900 | $1,962,200 |
| All families | $215,900 | $1,241,500 |
In 2025 dollars. The survey's family is the main person or couple in a household plus anyone financially interdependent with them, grouped by the age of its reference person.
The median, the family in the middle, is the better yardstick. The mean is pulled up by the wealthiest families: across all families it was $1,241,500, more than five times the median of $215,900. The example couple’s $196,200 is $40,600 above the $155,600 median for families headed by someone 35 to 44.
The numbers moved between the 2022 and 2025 surveys. Median net worth for families under 35 fell 23% to $33,000, while the median for the oldest families rose 37%. Homeownership makes a big difference too: the median net worth of homeowners was $458,900, compared with $10,600 for families who don’t own their home.Source 1
Net worth vs. income
Income is what you earn in a year; net worth is what you’ve built up over time. The two are linked: higher-income families tend to have higher net worth, because they generally save more.Source 1 But a high income doesn’t guarantee a high net worth if most of it gets spent. In the 2025 survey, median family income (for the year before) was $82,200, while median net worth was $215,900.Source 1
If your net worth is negative
You’re not alone. Among the quarter of families with the least wealth, median net worth was $1,700 in 2025, and their average was below zero.Source 1 Student loans or a new car loan can easily outweigh what you own early on. What matters most is the direction: a number that rises each year means your plan is working.
How to grow your net worth
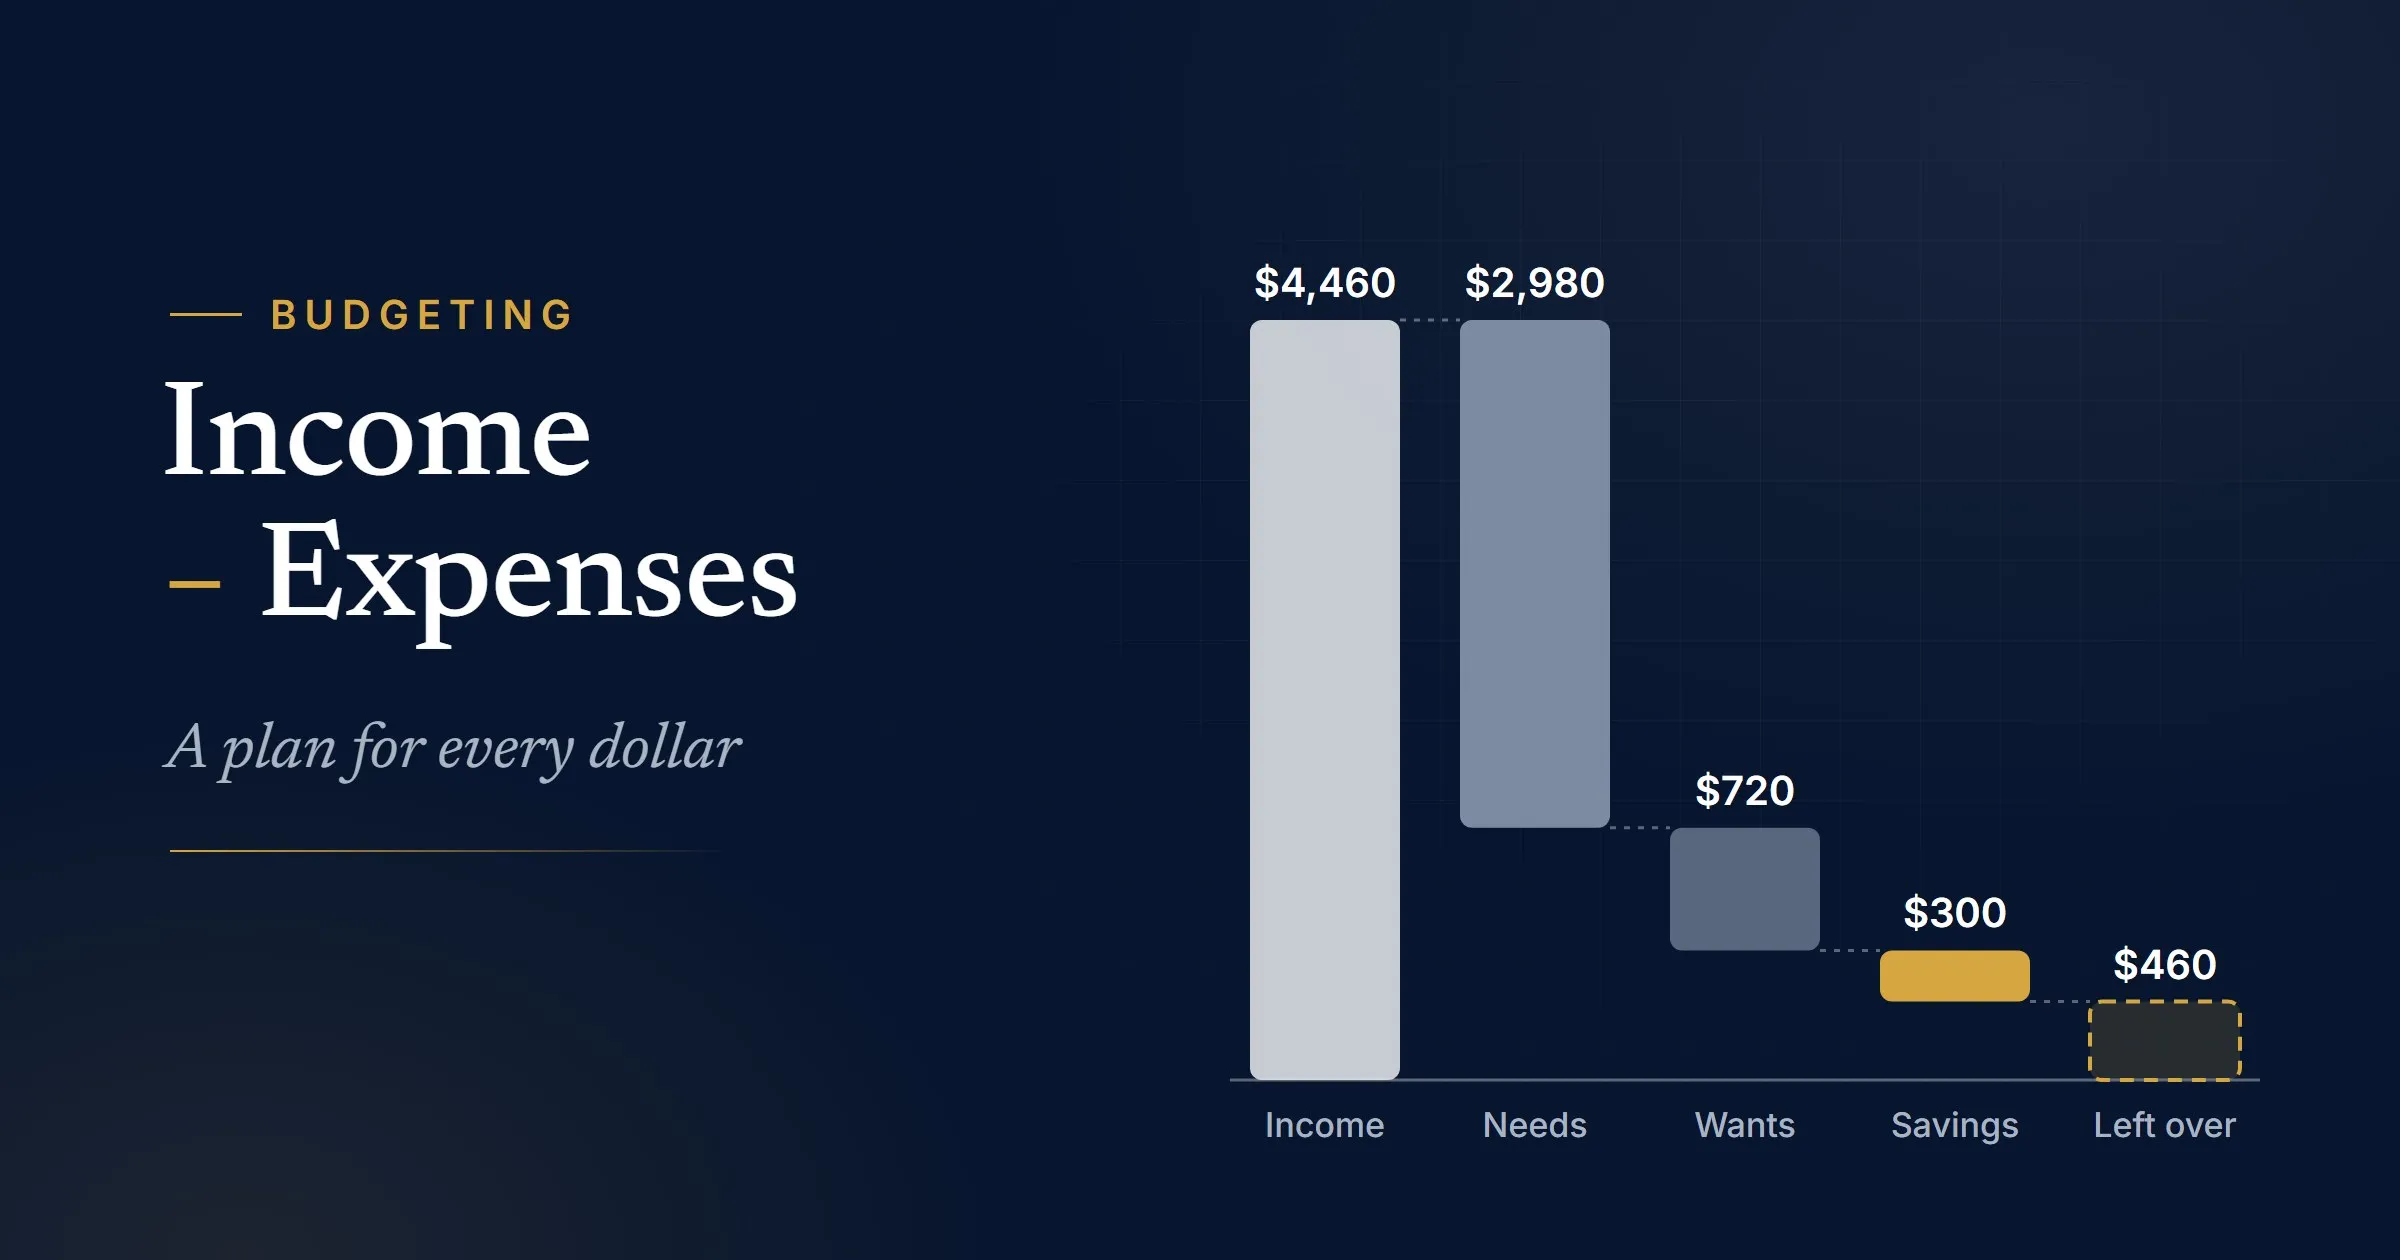
- Spend less than you earn. A budget makes the gap visible; our guide to making a budget walks through it.
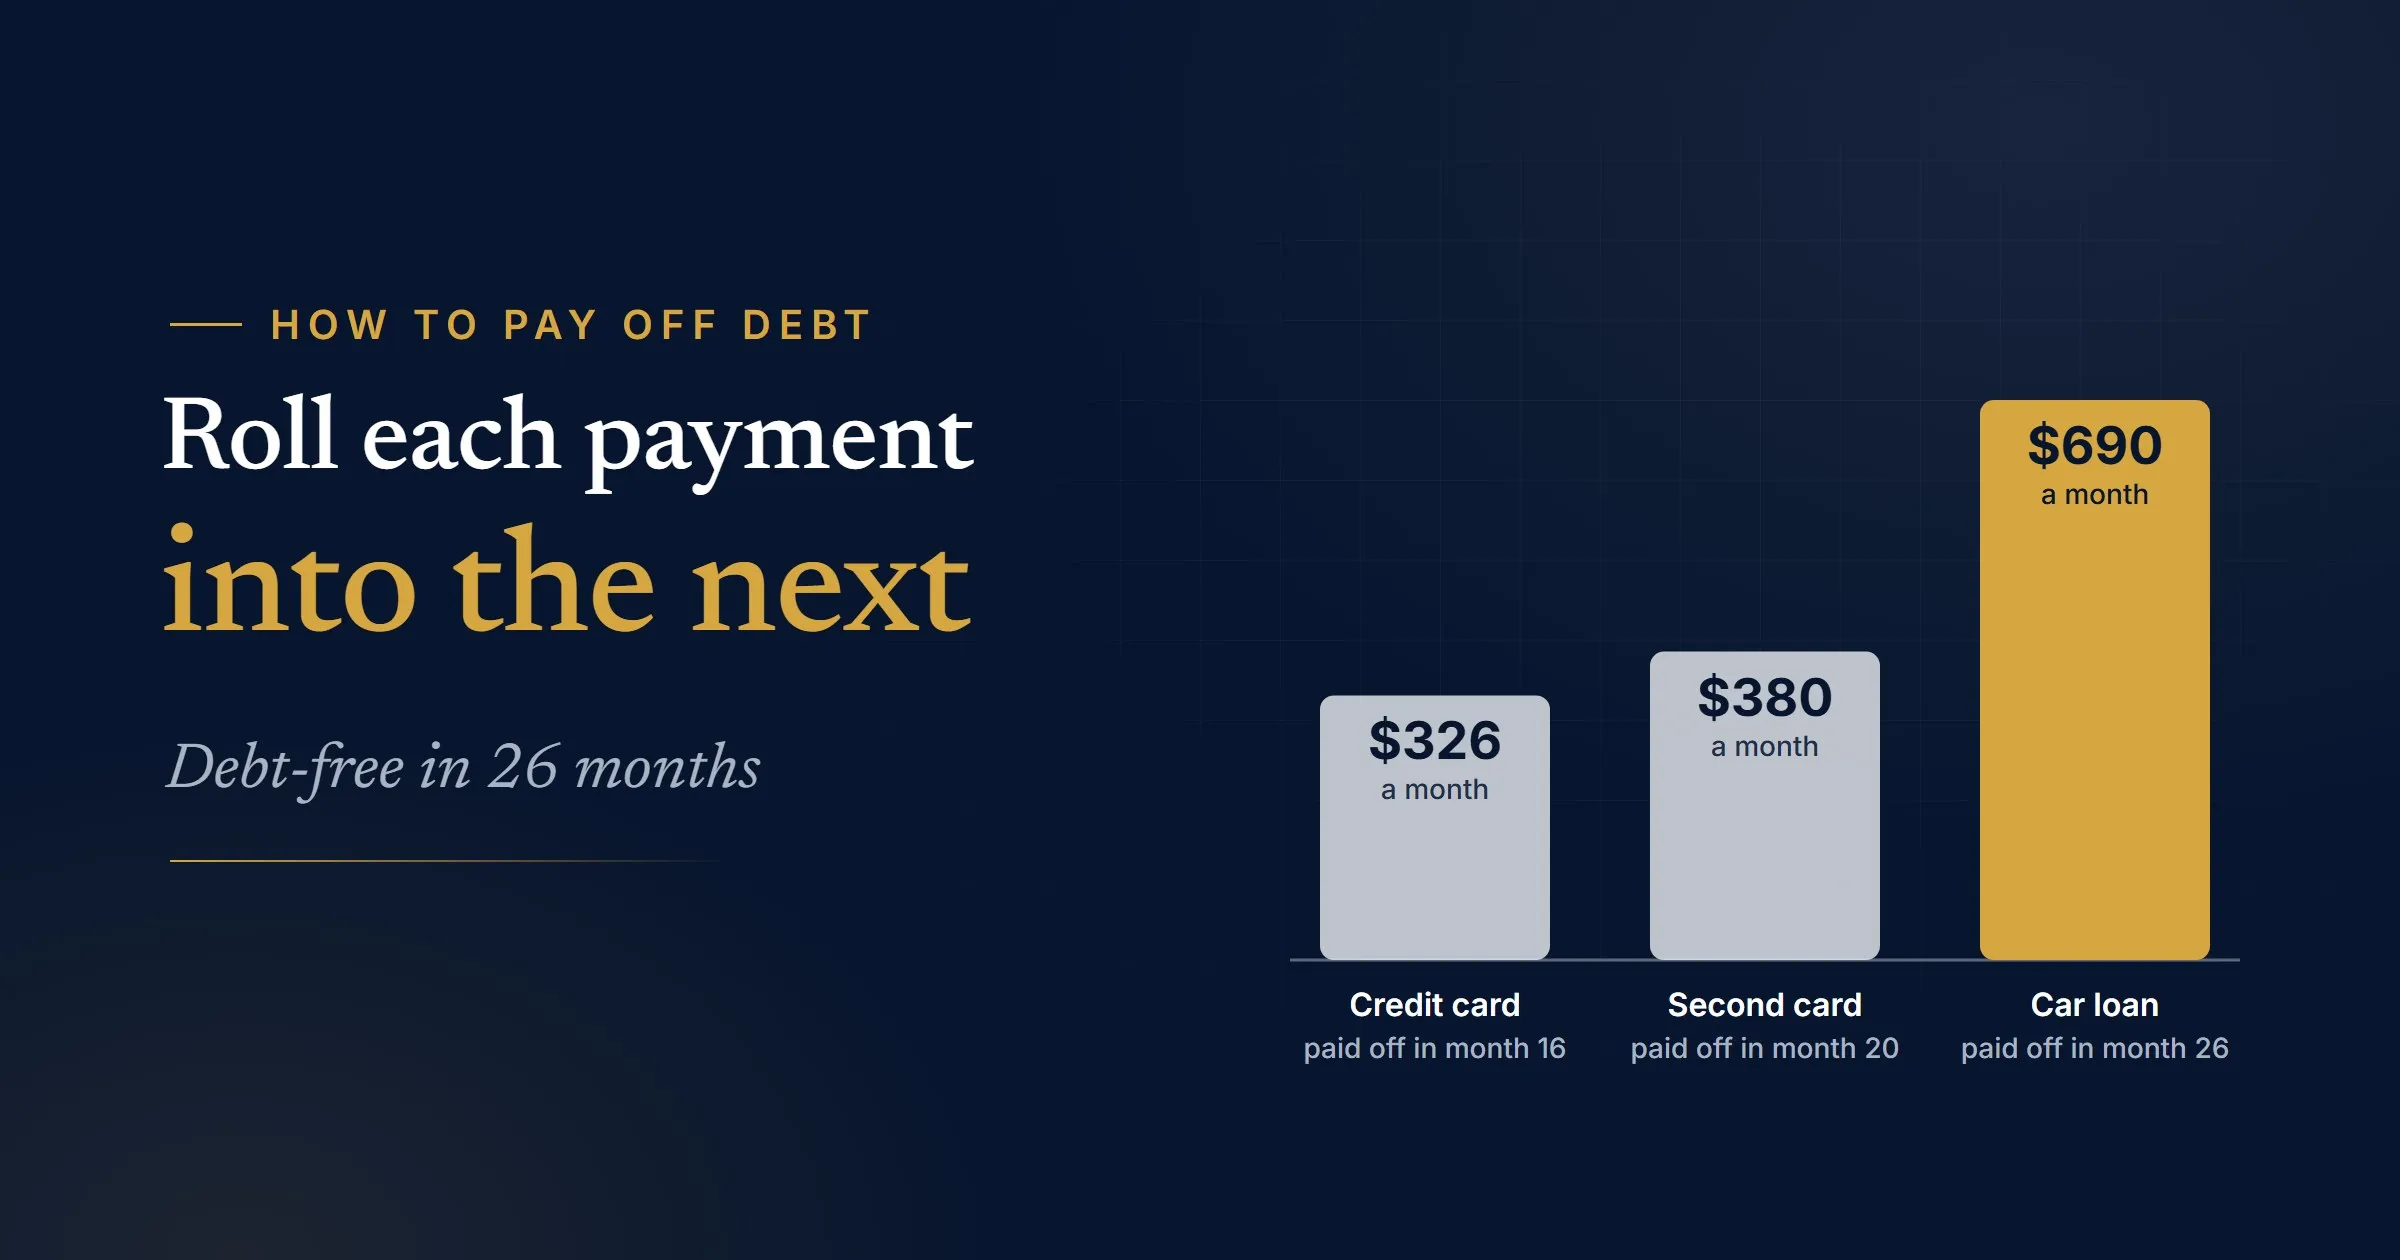
- Pay down high-interest debt. As the SEC’s Investor.gov puts it, no investment strategy pays off as well as, or with less risk than, eliminating high-interest debt.Source 2 Our guide to paying off debt shows how.
- Build an emergency fund, so a surprise expense doesn’t turn into new debt that can grow because of interest and fees.Source 3 See our emergency fund guide.
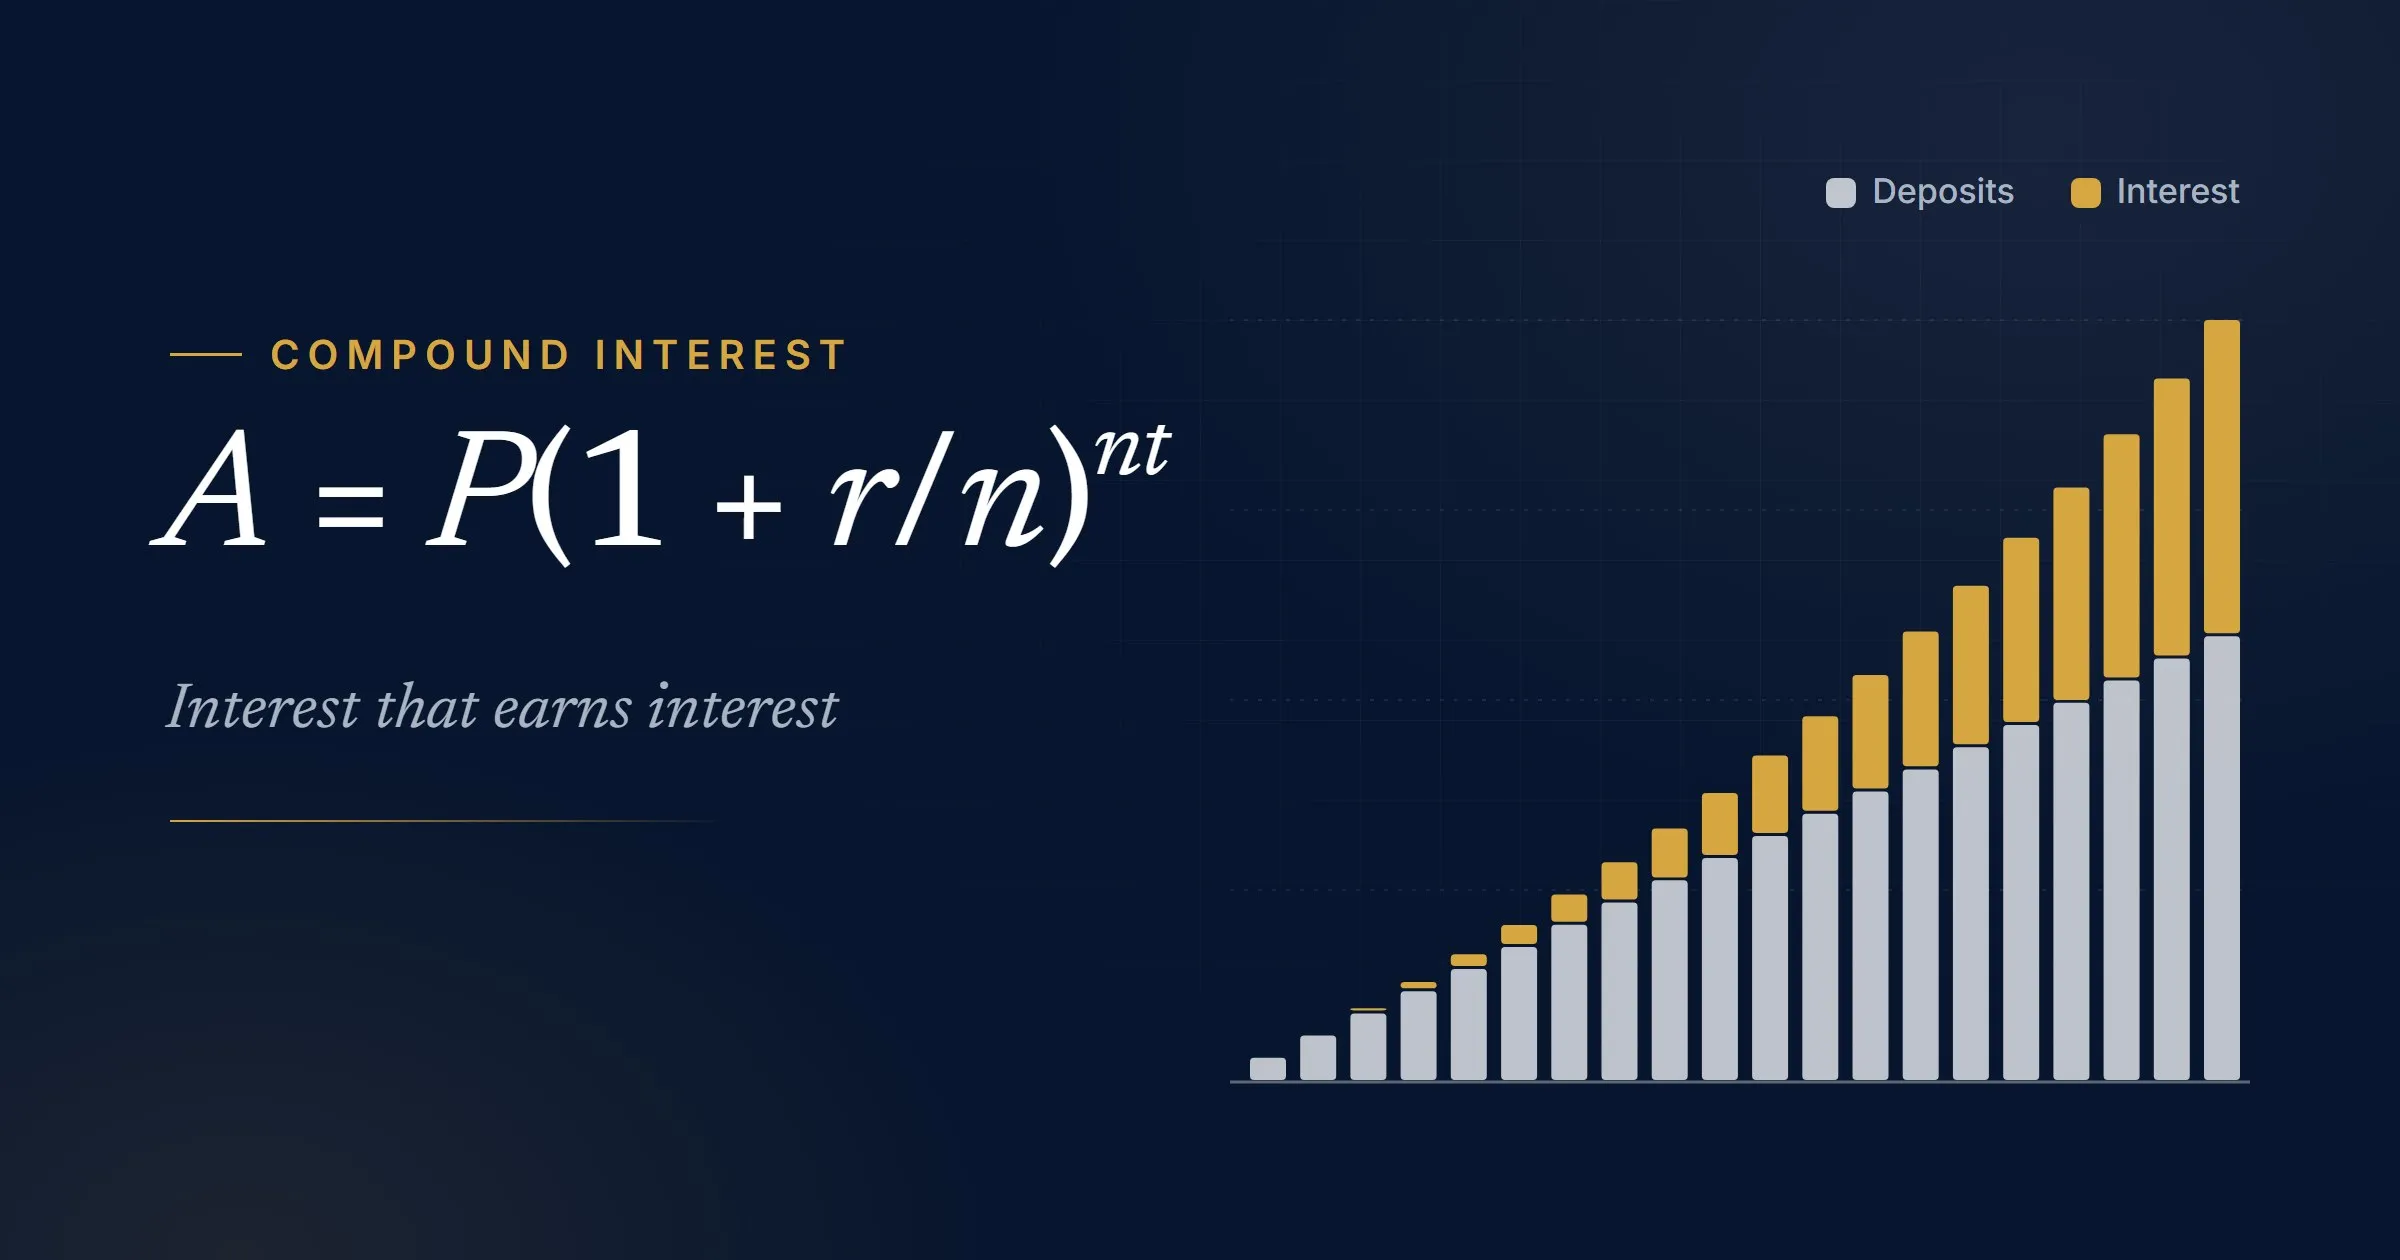
- Save and invest for the long term. Time lets compound interest do more of the work.
- Check it once or twice a year, on about the same date and with the same method.
Common questions
What is net worth in simple terms?
What you own minus what you owe. If you sold everything and paid off every debt, it’s roughly what you’d have left.
What’s a good net worth for my age?
There’s no single target, but the Federal Reserve’s medians by age show where the middle family stands. For families headed by someone 35 to 44, the 2025 median was $155,600.
Does net worth include my home?
Yes. Count your home at its estimated market value as an asset and your mortgage as a liability. The difference is your home equity.
Should I include retirement accounts?
Yes, at their current balances. The Federal Reserve counts retirement accounts such as 401(k)s and IRAs as assets.Source 1
What’s liquid net worth?
It usually means the part of your net worth you could turn into cash quickly, such as bank accounts and taxable investments, minus your debts. Retirement accounts are often left out, because withdrawals before age 59½ generally come with an extra 10% tax unless an exception applies.Source 4 Definitions vary, so check what’s being counted.
Is net worth the same as income?
No. Income is what you earn over a year. Net worth is what you have at a point in time after subtracting your debts.
Run your own numbers
See how money can grow over time, year by year.
Open the calculator
Sources
Numbers in the text link to these sources. We check them whenever we update this page.
- 1
Board of Governors of the Federal Reserve System · Published October 9, 2026 · Accessed November 19, 2026 · Back to text for source 1
- 2
Pay Off Credit Cards or Other High Interest Debt(external site)
Investor.gov, U.S. Securities and Exchange Commission · Accessed November 18, 2026 · Back to text for source 2
- 3
An essential guide to building an emergency fund(external site)
Consumer Financial Protection Bureau · Updated October 29, 2025 · Accessed November 18, 2026 · Back to text for source 3
- 4
Retirement topics - Exceptions to tax on early distributions(external site)
Internal Revenue Service · Updated November 13, 2026 · Accessed November 19, 2026 · Back to text for source 4
About the author
Wealthistry Editorial Team
Research, writing and editing
The team that researches, writes, fact-checks and updates Wealthistry's guides and calculators, following our published editorial standards.
Author profileEditorial policyHow we researchReport an error