FDIC insurance is the federal guarantee behind your bank deposits. If an FDIC-insured bank fails, the Federal Deposit Insurance Corporation protects your deposits up to the insurance limit, and since the FDIC was founded in 1933, no depositor has lost a penny of FDIC-insured funds.Source 1
You don’t have to apply or pay for it. Coverage is automatic whenever you open a deposit account at an FDIC-insured bank.Source 2 This guide explains the $250,000 limit, how joint, retirement and trust accounts are covered, worked examples, and what FDIC insurance doesn’t cover.
The FDIC insurance limit
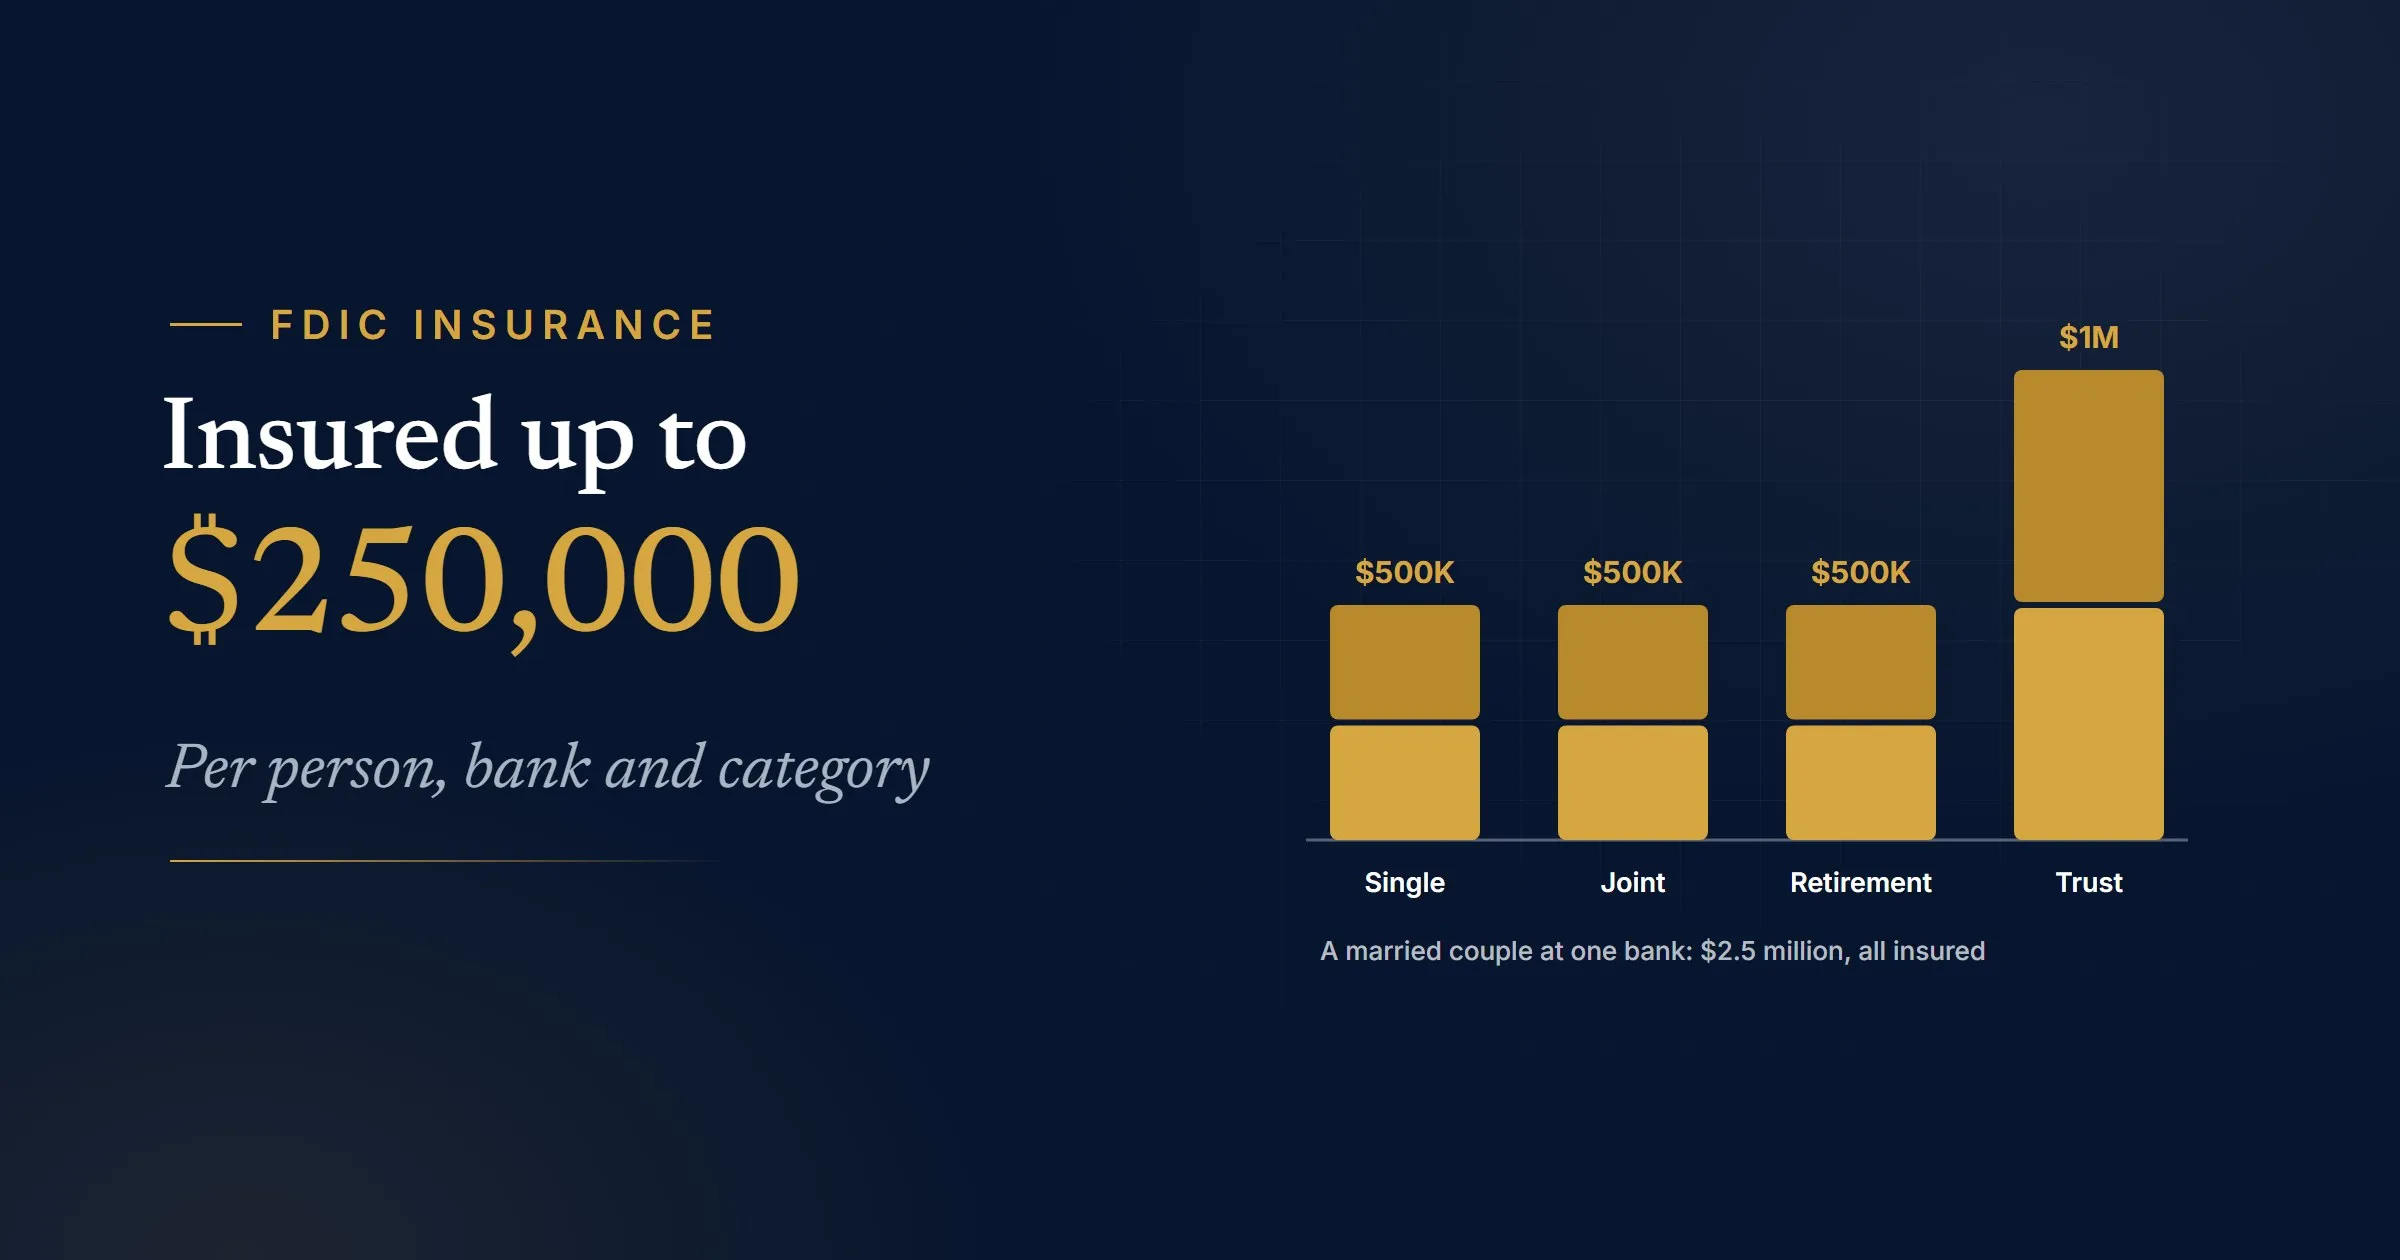
The standard limit is $250,000 per depositor, per FDIC-insured bank, for each account ownership category.Source 1 Each part of that rule matters:
- Per depositor. Each person is insured separately. The limit isn’t per account.
- Per bank. Deposits at different FDIC-insured banks are insured separately.
- Per ownership category. All your deposits in the same ownership category at the same bank are added together, but accounts in different categories, such as a savings account in your name and an IRA, are insured separately.Source 1
Insurance covers what you deposited plus any interest earned through the day the bank fails, all within the same limit.Source 2
What FDIC insurance covers, and what it doesn’t
FDIC insurance covers deposits, and only at FDIC-insured banks. It doesn’t cover investment products that aren’t deposits, even when an FDIC-insured bank sells them.Source 1
Covered:
- Checking accounts, including negotiable order of withdrawal (NOW) accounts
- Savings accounts
- Money market deposit accounts
- Certificates of deposit (CDs)
- Cashier’s checks, money orders and other official items issued by a bank
Not covered:
- Stocks, bonds and mutual funds
- Annuities and life insurance policies
- Safe deposit boxes and their contents
- U.S. Treasury bills, bonds and notes, and municipal securities
- Crypto assets
Ownership categories
The FDIC has several ownership categories, including ones for businesses, employee benefit plans and government accounts.Source 1 These four cover most personal accounts:Source 3
| Category | What it includes | Coverage |
|---|---|---|
| Single accounts | Accounts owned by one person, with no beneficiaries | $250,000 per owner |
| Joint accounts | Accounts owned by two or more people with equal rights to withdraw | $250,000 per co-owner, for their share of all joint accounts |
| Certain retirement accounts | IRAs, including Roth, SEP and SIMPLE IRAs, and self-directed 401(k) and Keogh plan accounts | $250,000 per owner, for all of them combined |
| Trust accounts | Payable-on-death accounts and revocable or irrevocable trusts | $250,000 per beneficiary, up to $1,250,000 per owner |
Joint accounts
Each co-owner’s shares of every joint account at the same bank are added together and insured up to $250,000, and the FDIC assumes the shares are equal unless the bank’s records say otherwise.Source 3 So a joint account for two people is insured up to $500,000. If the same two co-owners keep $600,000 in joint accounts at one bank, $500,000 is insured and $100,000 isn’t.
To qualify, every co-owner must be a living person with equal rights to withdraw. Each must also have signed the account’s signature card, or be shown as a co-owner in the bank’s records, though that isn’t required for CDs.Source 3
Retirement accounts
The FDIC adds together the deposits in all the eligible retirement accounts one person owns at the same bank, such as an IRA held in a CD, and insures the total up to $250,000. Naming beneficiaries on these accounts doesn’t increase the coverage.Source 3
Trust accounts
Payable-on-death accounts and revocable and irrevocable trusts are insured for $250,000 per owner for each eligible beneficiary, up to $1,250,000 per owner with five or more beneficiaries. That limit applies to all of an owner’s trust accounts at the same bank combined, and it has been in place since April 1, 2024.Source 3 An owner who names three beneficiaries is insured up to $750,000; naming six still tops out at $1,250,000.
FDIC insurance examples
One person over the limit
You have three accounts in your own name at one bank: $35,000 in checking, $180,000 in savings and a $60,000 CD. All three are single accounts, so they’re added together. Of the $275,000, $250,000 is insured and $25,000 isn’t.
There are two simple fixes. Move the extra to a different FDIC-insured bank, or name a beneficiary on the CD. A payable-on-death CD falls into the trust category, which is insured separately, so all $275,000 becomes insured. Check how a beneficiary fits your plans before you add one.
A married couple at one bank
By using every personal ownership category, a married couple could keep $2,500,000 at one bank and have all of it insured:
| Account | Ownership category | Insured |
|---|---|---|
| Spouse A's savings | Single | $250,000 |
| Spouse B's savings | Single | $250,000 |
| Joint checking and savings | Joint | $500,000 |
| Spouse A's IRA CD | Retirement | $250,000 |
| Spouse B's IRA CD | Retirement | $250,000 |
| Spouse A's account payable on death to their two children | Trust | $500,000 |
| Spouse B's account payable on death to their two children | Trust | $500,000 |
| Total | $2,500,000 |
Each spouse's payable-on-death account names the same two children as beneficiaries.
A CD that earns interest
Because interest counts toward the limit, leave room for it. A $240,000 CD in your name earning 4% APY grows to $249,600 after a year, still fully insured. If the interest stays in the CD for a second year, the balance reaches $259,584, and $9,584 is over the limit. Our APR vs. APY guide explains how APY works.
How to check your coverage
- Confirm the bank is insured. Ask the bank, look for the FDIC sign at a branch, or search the FDIC’s BankFind tool.Source 2
- Estimate your coverage. The FDIC’s Electronic Deposit Insurance Estimator (EDIE) calculates how much of your money is covered.Source 1
- Ask the FDIC. You can call 1-877-ASK-FDIC (1-877-275-3342) or use its online support center.Source 2
Money apps and pass-through insurance
Nonbank companies, including many money apps, are never FDIC-insured themselves. Money you send to one isn’t eligible for FDIC insurance until the company deposits it at an FDIC-insured bank and other conditions are met. Then it may qualify for what’s called pass-through coverage if that bank fails. FDIC insurance doesn’t protect you if the nonbank company itself goes bankrupt.Source 4
Before you keep savings in an app, find out which bank holds the money, confirm that bank in BankFind and read the disclosures to see whether your account may be eligible.Source 4
What happens if a bank fails
Historically, the FDIC has paid insured deposits within a few days of a bank closing, usually the next business day. It either gives each depositor a new account at another insured bank for the insured balance or sends a check.Source 2
Money above the limit isn’t automatically lost. Depositors may get back part of their uninsured funds as the failed bank’s assets are sold, but that can take several years.Source 2
Credit unions: NCUA insurance
Credit unions have their own version. Established by Congress in 1970, the National Credit Union Share Insurance Fund insures member accounts at federally insured credit unions, and it’s backed by the full faith and credit of the United States. It covers individual accounts up to $250,000, a member’s share of all joint accounts up to $250,000, and IRA and Keogh retirement accounts separately up to $250,000. No one has lost a penny of insured deposits at a federally insured credit union.Source 5
Coverage is automatic when you join, and the NCUA’s Share Insurance Estimator works like the FDIC’s EDIE.Source 5 Our checking vs. savings guide covers choosing accounts at a bank or credit union.
Common questions
What does FDIC insured mean?
That your deposits at an FDIC-insured bank are protected, up to the insurance limit, if the bank fails.
Is the FDIC limit per account?
No. It’s $250,000 per depositor, per bank, for each ownership category. Several accounts in the same category at the same bank share one limit.
How does FDIC insurance work for joint accounts?
Each co-owner is insured up to $250,000 for their share of all joint accounts at the same bank, so two co-owners are covered up to $500,000 together.
Are CDs FDIC insured?
Yes. CDs at FDIC-insured banks are deposits, covered under the same limits as your other accounts in the same ownership category. Interest counts toward the limit.
Is a high-yield savings account FDIC insured?
It is if it’s a deposit account at an FDIC-insured bank. If you opened it through an app that isn’t a bank, it’s insured only if the money is deposited at an insured bank and the requirements for pass-through coverage are met. Our high-yield savings guide covers how these accounts work.
How can I insure more than $250,000?
Spread your money across more than one FDIC-insured bank, or use different ownership categories at one bank, such as joint, retirement and trust accounts.
Sources
Numbers in the text link to these sources. We check them whenever we update this page.
- 1
Understanding Deposit Insurance(external site)
Federal Deposit Insurance Corporation · Updated April 1, 2024 · Accessed November 18, 2026 · Back to text for source 1
- 2
Deposit Insurance FAQs(external site)
Federal Deposit Insurance Corporation · Updated April 1, 2024 · Accessed November 19, 2026 · Back to text for source 2
- 3
Your Insured Deposits(external site)
Federal Deposit Insurance Corporation · Updated May 14, 2024 · Accessed November 19, 2026 · Back to text for source 3
- 4
Banking With Third-Party Apps(external site)
Federal Deposit Insurance Corporation · Updated May 31, 2024 · Accessed November 19, 2026 · Back to text for source 4
- 5
Share Insurance Coverage(external site)
National Credit Union Administration · Updated November 18, 2026 · Accessed November 18, 2026 · Back to text for source 5
About the author
Wealthistry Editorial Team
Research, writing and editing
The team that researches, writes, fact-checks and updates Wealthistry's guides and calculators, following our published editorial standards.
Author profileEditorial policyHow we researchReport an error